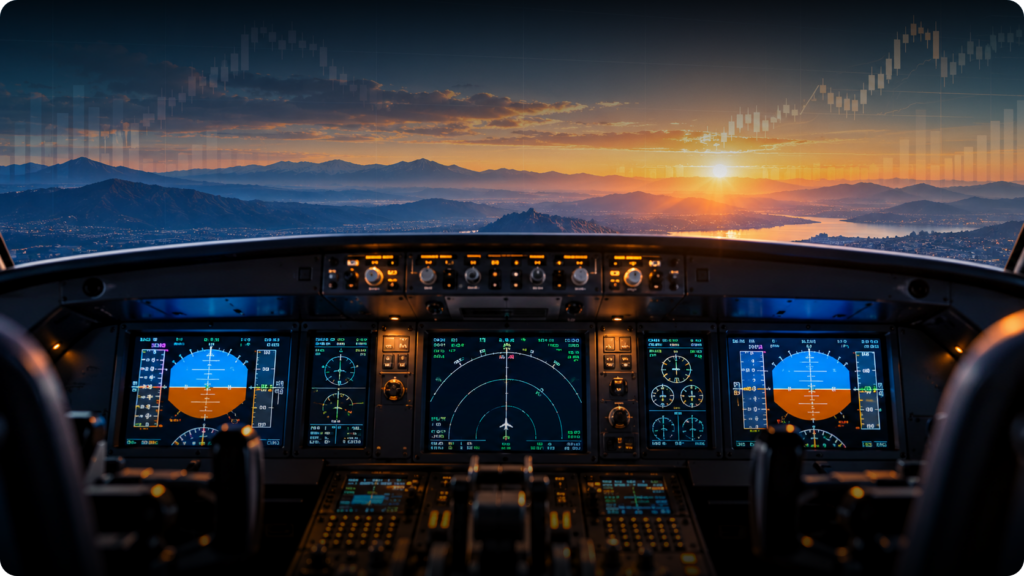
The Instrument Panel Is Flashing:
Rates, Inflation, AI, and Year-End Planning
Before a pilot takes off, they do not check only one gauge. They scan the full instrument panel: fuel, altitude, weather, engine pressure, navigation, and backup systems. One warning light may matter, but it rarely tells the whole story by itself.
Markets feel similar right now.
Inflation is still elevated. The Federal Reserve raised rates in September. Long-term Treasury yields are near multi-decade highs. Oil prices remain volatile because of geopolitical tensions. Consumer confidence is weak. Hiring has slowed. And yet, broad equity markets remain near record levels, supported by resilient earnings, AI-related investment, and an economy that continues to expand.
This is not a simple environment. But most important financial decisions are rarely made in simple environments.
At Strategic Income Group, we believe the key is not reacting to one flashing light. It is understanding the full dashboard, then making sure your plan is still built for the road ahead.
What Happened This Month
The biggest shift this month is that the Federal Reserve is no longer simply “waiting to cut.” In September, the Fed raised the target range for the federal funds rate by 0.25% to 3.75%–4.00%, citing elevated inflation while also noting that economic activity continues to expand at a solid pace, domestic spending remains resilient, productivity growth is strong, and job gains have generally kept pace with the workforce. Federal Reserve
That rate increase matters because it came at a time when other parts of the economy are already feeling pressure. The latest CPI report showed that prices rose 3.4% year-over-year in August, with energy prices up 16.3% and gasoline up 27.4%. Core CPI, which excludes food and energy, rose 2.4% year-over-year. That tells us inflation is not as broad-based as it was during the peak inflation years, but energy remains a major pressure point for households and businesses. Bureau of Labor Statistics
The labor market is also sending a more cautious signal. The September jobs report showed only 29,000 new jobs, with unemployment at 4.2%. Payroll gains in July and August were revised down by a combined 60,000 jobs, and average hourly earnings rose 3.0% over the prior year. In plain English: layoffs remain low, but hiring has clearly slowed. Bureau of Labor Statistics
Markets, however, have remained resilient. On October 8, the S&P 500 was still up 13.4% year-to-date, the Nasdaq was up 17.0%, the Dow was up 6.6%, and the Russell 2000 was up 12.6%. The S&P 500 and Nasdaq pulled back that day on technology weakness, but the broader market remained close to record territory. AP News
That combination—slower hiring, higher rates, elevated oil prices, and strong markets—is exactly why clients may feel like the signals are conflicting.
They are.
The Fed’s Balancing Act: Inflation vs. Employment
The Federal Reserve’s dual mandate is to pursue price stability and maximum employment. Right now, those two goals are pulling in different directions.
Inflation is still above the Fed’s 2% target, and energy prices have made the inflation story more complicated. At the same time, job growth has slowed meaningfully. The September jobs report was weak, but not recessionary. Unemployment remains relatively low, but the pace of hiring has cooled.
This creates a difficult policy environment. If the Fed raises rates too aggressively, it risks putting more pressure on hiring, housing, credit markets, and business investment. If it does too little, inflation could become more persistent.
Recent Fed commentary reflects that tension. Minutes and public comments suggest policymakers are divided over how quickly to move from here. Some want more tightening to fight inflation, while others appear more cautious given the softer labor data. Markets are currently debating whether the Fed pauses at the October meeting and considers another increase later in the year. Reuters
For clients, the planning takeaway is straightforward: we should not assume rates are about to fall quickly. Higher-for-longer may still be the environment we are operating in.
That affects cash yields, bond values, mortgage rates, business financing, real estate, private credit, and retirement income planning.
Oil remains one of the most important economic variables heading into year-end. The conflict involving Iran and the Strait of Hormuz continues to create uncertainty, and energy prices remain highly sensitive to headlines.
On October 9, AP reported Brent crude at roughly $104.15 per barrel, while the 10-year Treasury yield was around 5.24%. Those two numbers together are important: high oil can keep inflation elevated, and high Treasury yields can keep borrowing costs elevated. AP News
Oil affects far more than gasoline. It flows through transportation, airline costs, shipping, food, manufacturing, utilities, and consumer confidence. When energy prices rise quickly, many households feel it almost immediately.
That does not mean oil prices alone will derail the economy. The U.S. is in a stronger energy position than it was decades ago, and markets have become better at adjusting to shocks. But energy volatility can still affect inflation expectations, Fed policy, and consumer behavior.
For retirees and income-focused clients, this is why inflation assumptions matter. For business owners and families still accumulating wealth, it is why cash flow and liquidity matter. And for all clients, it is a reminder that a financial plan should be built with room for unexpected cost pressures.
Markets: Strong, but Narrow and Expensive in Places
Markets have been strong this year, but the strength is not evenly distributed.
A Reuters report noted that the current AI-centered bull market is approaching its four-year anniversary and that the S&P 500 has gained roughly 117% since its October 2022 low. That same report also highlighted a growing concentration risk: the top 10 companies in the S&P 500 now represent about 40% of the index. Reuters
That does not mean the market is wrong. AI-related investment may continue to support earnings, productivity, and business investment. Many of these companies are highly profitable and remain central to the economy.
But concentration matters. When a small group of companies drives a large portion of returns, investors should be careful not to confuse index strength with broad market health.
This is also why we do not want clients thinking only in terms of “the S&P 500.” SIG clients may own public equities, public bonds, private credit, private equity, hedge or alternative strategies, cash, and other planning-based allocations depending on their personal situation. The goal is not simply to participate in a market index. The goal is to align every investment bucket with the client’s actual financial plan.
Higher rates are not just a Wall Street topic. They are showing up in daily financial decisions.
Mortgage rates have moved sharply higher. Reuters reported the average 30-year fixed mortgage rate recently reached 7.40%, the highest since November 2023. That affects affordability, housing activity, refinancing, real estate transactions, and family planning decisions around buying or selling property. Reuters
Higher rates can be positive for savers and income-oriented investors, but they also increase the cost of borrowing and can pressure asset valuations. For retirees, higher yields may create income opportunities. For business owners, higher rates may change borrowing decisions. For younger families, higher mortgage rates may affect housing affordability. For investors, higher bond yields may compete with equities for capital.
This is why interest rates are not just an economic data point. They connect directly to life decisions.
One of the more concerning signals is consumer confidence. The Conference Board’s Consumer Confidence Index fell by 6.7 points in September to 81.9, and the Expectations Index declined for the third consecutive month to 63.6. The survey period included both the Fed rate hike and ongoing geopolitical tensions. The Conference Board
The University of Michigan’s preliminary October consumer sentiment reading also fell to 46.3, near record lows, with short-term inflation expectations rising to 4.7% and long-term expectations rising to 3.5%. Reuters
That gap between markets and consumers is important. Markets can rise because of earnings growth, AI spending, productivity, or expectations about the future. But families make decisions based on what they feel: groceries, gas, insurance, housing, utilities, and job security.
This is another reason we believe planning matters. The market may be strong, but if your personal cash flow feels tight, your plan needs to reflect that reality.
The question is not:
The better question is:
A good plan should not rely on one perfect outcome.
It should be able to handle different environments: higher rates, lower rates, strong markets, weak markets, inflation spikes, energy volatility, changes in tax law, health events, family needs, and unexpected opportunities.
At SIG, we believe planning should drive investment decisions. Markets create headlines. Your plan creates context.
For Clients in the Accumulation Phase
If you are still building wealth, this is a time to remain disciplined while also being opportunistic.
Strong markets may have pushed certain allocations above target. That does not automatically mean something is wrong, but it may create a good opportunity to review rebalancing, concentrated positions, or tax-loss harvesting. For clients with taxable accounts, custom indexing or other tax-aware strategies may be worth discussing if they fit the plan.
Higher interest rates also make cash more attractive than it was for many years. But cash should still have a purpose. Emergency reserves, upcoming purchases, tax payments, and short-term goals are valid reasons to hold cash. Long-term wealth-building dollars should not drift into cash simply because headlines feel uncomfortable.
This is also a good time to check contribution progress. Are you on track with 401(k), 403(b), HSA, backdoor Roth, after-tax savings, education funding, or other planned contributions? Waiting until December often limits flexibility.
For business owners, executives, and clients with concentrated stock or liquidity events, the fourth quarter is also a time to coordinate investment decisions with tax planning.
For Clients in the Strategic Income Phase
If you are retired or nearing retirement, the current environment is a reminder that retirement income planning is about more than portfolio returns.
Higher rates can help income generation, but they also increase volatility in bond prices and create stress in real estate, credit markets, and borrowing-sensitive areas. Higher inflation affects spending assumptions. Higher oil prices can flow through travel, food, utilities, and healthcare costs. Market concentration can create portfolio risk if growth assets are too dependent on a narrow group of companies.
This is why bucket planning matters.
Your Reserve Bucket should support near-term liquidity. Your Income and Income+ Buckets should help provide cash flow over the intermediate term. Your Long-Term Growth Bucket should be positioned for future inflation, legacy, and longer-term goals.
For Strategic Income clients, October is a practical month to review upcoming withdrawals, RMDs, QCDs, charitable giving, tax withholding, Medicare open enrollment, and any major expenses planned before year-end.
Medicare Open Enrollment runs from October 15 through December 7, and CMS notes that plans can change costs, coverage, provider networks, and pharmacy networks each year. Clients on Medicare should review their Annual Notice of Change and compare coverage if appropriate. Centers for Medicare & Medicaid Services
What Clients Should Review Before Year-End
October is early enough to be proactive and late enough that year-end decisions are becoming real.
Here are a few areas worth reviewing now:
Tax planning. Review realized gains and losses, charitable giving, Roth conversion opportunities, tax withholding, estimated payments, and whether any tax-loss harvesting opportunities exist.
Income planning. Confirm upcoming withdrawals, RMD timing, QCDs if eligible, and whether cash reserves are sufficient for near-term needs.
Portfolio alignment. Review whether market gains or market rotations have caused drift from the intended allocation.
Cash strategy. Confirm that cash is doing its job. Too little cash can create stress; too much cash can create long-term opportunity cost.
Charitable giving. Consider whether giving should be completed through cash, appreciated securities, donor-advised funds, or QCDs, depending on your situation.
Insurance and healthcare. Review Medicare plans, employer benefits, long-term care considerations, life insurance, disability coverage, and umbrella liability coverage where appropriate.
Estate and legacy. Confirm beneficiary designations, trust funding, powers of attorney, healthcare directives, and whether any family or life changes require updates.
At SIG, we are watching inflation, oil prices, Fed policy, interest rates, market concentration, consumer confidence, employment, credit conditions, and year-end planning opportunities.
We are not looking only at one number or one index. We are reviewing how the full picture affects client portfolios, income plans, tax planning, charitable strategies, and long-term goals.
We are also paying attention to where markets may be overconfident. AI remains a powerful long-term theme, but concentration risk is real. Fixed income yields are more attractive, but rate risk is real. Cash yields are helpful, but reinvestment risk is real. Private markets and alternatives may provide diversification for some clients, but complexity, liquidity, and suitability matter.
Our job is to evaluate these opportunities through the lens of your plan—not through the emotion of the moment.
Closing Thought
When the instrument panel is flashing, the worst thing a pilot can do is stare at one gauge and ignore the rest.
The same is true in financial planning.
Inflation matters. Rates matter. Oil matters. The labor market matters. AI matters. Taxes matter. But none of them should be viewed in isolation.
At Strategic Income Group, our mission remains:
Markets will continue to change. Headlines will continue to compete for attention. Our focus is helping your wealth remain aligned with your life, your family, your purpose, and your legacy.
If you do not already have a year-end review scheduled, this is a good time to connect with your SIG Financial Planner.
YOUR NEXT STEP
Bring the full picture into focus.
Have questions about interest rates, your income strategy, taxes, or year-end planning? Schedule a conversation with your Strategic Income Group financial planner.
Prefer to call? (480) 466-7070
This article is for educational purposes only and should not be considered individualized financial, investment, tax, legal, insurance, or Medicare advice. Your situation is unique, and decisions should be made in coordination with qualified professionals who understand your full financial picture.
Investment strategies involve risk, including the possible loss of principal, and no strategy can guarantee results. Diversification and asset allocation do not guarantee a profit or protect against loss in declining markets. Indexes are unmanaged, do not reflect advisory fees or expenses, and cannot be invested in directly.
Any strategy discussed may not be suitable for every investor. Suitability depends on your goals, risk tolerance, risk capacity, time horizon, liquidity needs, tax situation, eligibility, and overall financial plan. Alternative and private-market investments may involve additional risks, including illiquidity, complexity, valuation uncertainty, limited transparency, higher fees, and possible loss of principal.
Tax and estate-planning strategies should be reviewed with your CPA and attorney. Medicare decisions should be reviewed with a qualified Medicare professional or Medicare.gov. Market conditions, tax rules, laws, plan availability, and coverage options can change.
Strategic Income Group is an SEC-registered investment adviser. Registration does not imply a certain level of skill or training.